
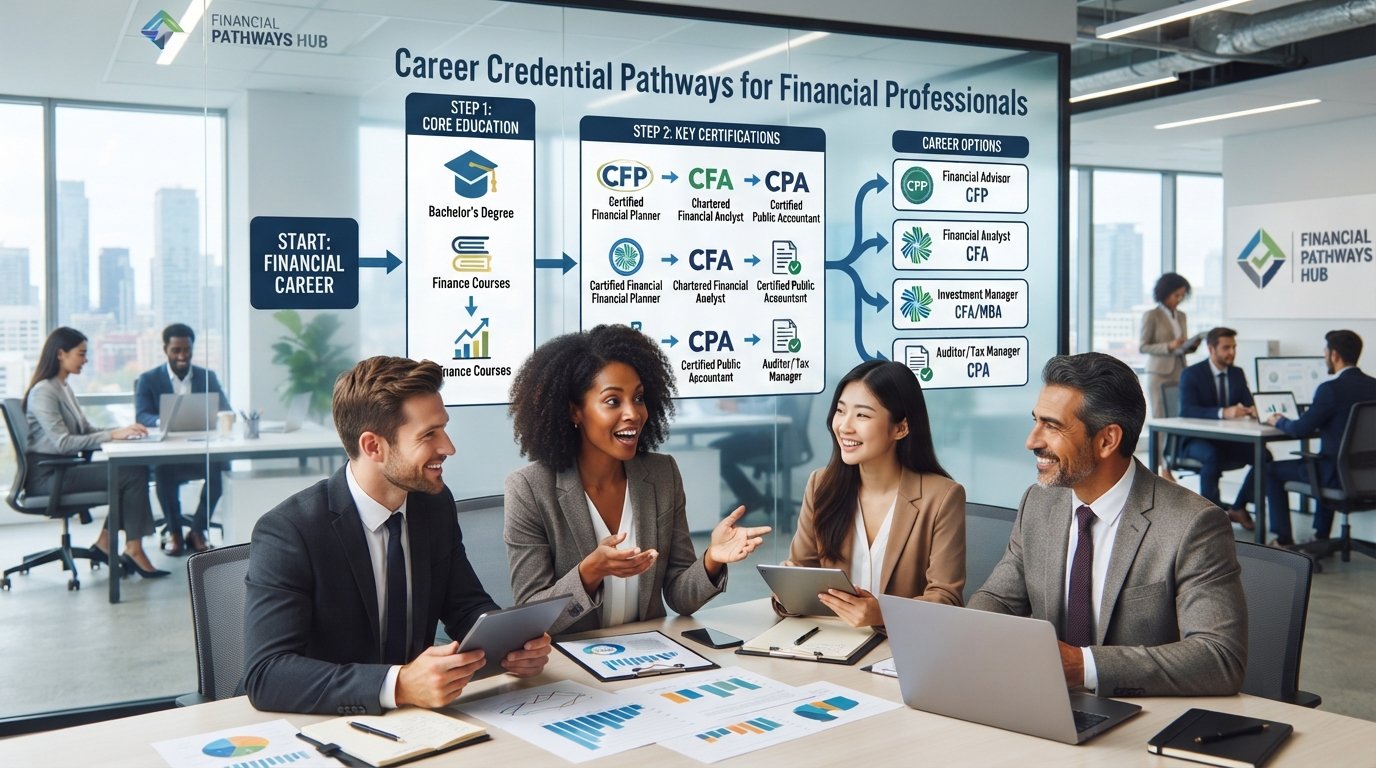
A credential can shape the work you do and the people you serve. The Series 65, CFP®, ChFC®, WMCP®, and FSCP® offer different paths for early-career professionals. Some focus on broad financial planning, while others build investment skills or support practice management.
The Series 65 is a license for fee-based investment advice. Other options emphasize planning, portfolio knowledge, or business growth. The College offers WMCP® and FSCP® programs among these routes. Each certification has its own demands, so weigh your education, exam preparation, experience, and interests before you choose a second certification.
Think about the clients you hope to serve and the skills you want to build. The right path should fit your role today and your goals for the future—not just look impressive. This overview can help you compare options and find a useful next step in finance.
Key Takeaways
- Credentials can open different career options.
- Series 65 supports fee-based investment advice.
- Other routes focus on planning, portfolios, or practice growth.
- Education, exams, and experience affect your choice.
- Match your path to your clients and skills.
Financial advisor certifications and the career paths they can open
More than 100 certifications are available, so a title alone may not tell you what an advisor can do. Each certification signals different training, duties, and client needs. Compare the knowledge and skills behind each designation, not just its name. A license and a professional designation also serve different purposes.
“Choose a path for the work you want to do, not for the letters after your name.”
How designations differ from professional licenses
The Series 65 is a license, not a designation. NASAA develops its exam, and FINRA administers it. The CFP® mark and other designations reflect separate education and certification pathways. They may support broad financial planning, investment work, or management roles.
Why your career goals should guide your choice
Start with the work you hope to do. You might focus on tax, business growth, portfolio management, or planning for individual clients. Your goals, experience, and preferred clientele can help narrow the options. For years of practice ahead, choose a certification that builds relevant skills.
When comparing advisors, ask about their typical clients, continuing education, and compensation. These details reveal more than a credential alone and help you understand the services a client may receive.
Start with foundational licenses and entry-level credentials
A first license can help you test whether market-focused work suits your strengths. The Series 65 can be an early step toward becoming an investment advisor representative and offering advice for a fee.
NASAA develops the exam, and FINRA administers it. There are no prerequisites. The exam covers securities laws and rules, ethics, and core investment concepts.
“A license can open the door; continued learning helps you serve well.”
Series 65 and the path to fee-based investment advice
Passing the exam creates a licensing foundation, but it does not replace the broad education many clients seek. You can build knowledge through further study, then consider a certification or designation that fits your goals.
- Use this entry point to explore finance and investment work.
- Build skills in planning, investment management, or a specialty.
- Compare each program’s education, exam, and experience requirements.
Over the years, added learning can support stronger service for each client. A license allows a distinct role; additional certifications may expand what you know and how you work with clients.
| Series 65 feature | What it means | Next step |
|---|---|---|
| Entry requirements | No prerequisites | Review the exam topics |
| Core focus | Rules, ethics, and investment concepts | Build broader planning knowledge |
| Career purpose | Path to fee-based investment advice | Consider further education |
Build broad financial planning expertise
Comprehensive training can help you connect a client’s retirement, tax, estate, insurance, and investment needs. Compare each route’s coursework, exam, and experience rules with the work you want to do.
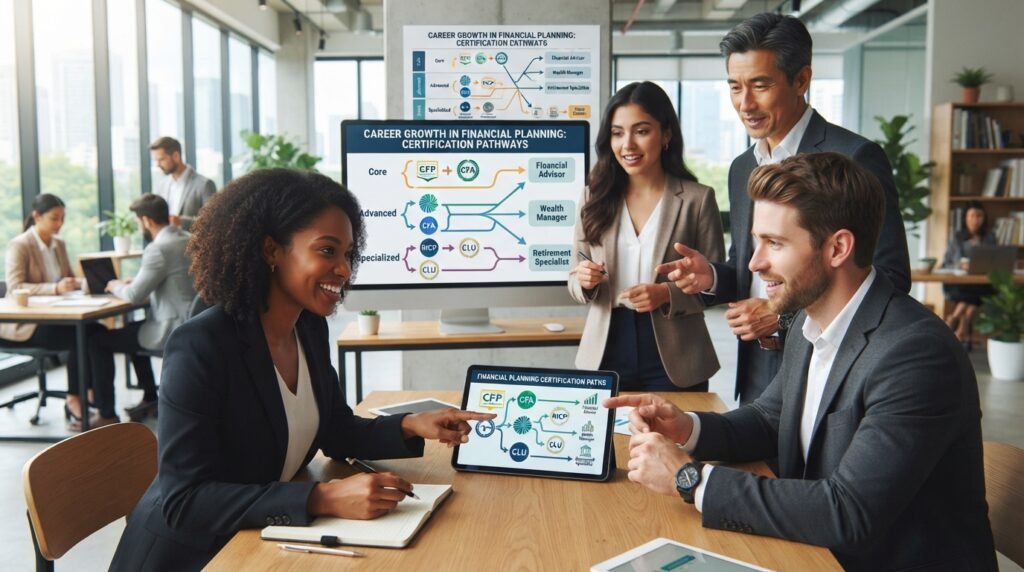
CFP® certification for comprehensive client planning
The CFP® certification requires a bachelor’s degree, a CFP Board Registered Program, an exam, relevant experience, and a commitment to ethics. The experience requirement is three years. CFP® professionals also complete 30 continuing-education hours every two years.
The College’s education program can take as few as seven months, with exam pass rates consistently above the national average. This broad preparation may suit you if your goals include helping clients coordinate complex planning needs.
ChFC® and CRPC® for applied planning and retirement guidance
The Chartered Financial Consultant (ChFC®) route offers case-based study in areas such as behavioral finance, risk management, and small-business planning. You can enroll without a bachelor’s degree, and many learners finish in eight months. The American College pathway meets CFP® exam education requirements and cites a three-year business-experience requirement.
ChFC® advisors report higher client-retention and earnings growth than peers without a designation. For a focused retirement path, compare CRPC® training as well. Choose the program that best fits your clients, skills, and intended scope of service.
Develop investment management and portfolio expertise
Investment-focused programs can deepen your portfolio skills and help you serve clients with complex needs. Compare the course load, exams, and experience rules with your career goals before choosing a path.
WMCP® for goal-based wealth management
The Wealth Management Certified Professional® (WMCP®) program covers goal-based planning, efficient portfolios, and wealth management strategies. Its three courses may take as few as three months. WMCP® designees report stronger growth in earnings, client numbers, and retention than professionals without a designation: 32%, 28%, and 144%, respectively.
CIMA® for serving high-net-worth clients
The Certified Investment Management Analyst® (CIMA®) path often takes six to nine months. Coursework covers portfolio design, risk, and related investment topics. The Investments and Wealth Institute reports that 94.5% of surveyed people rate the credential highly valuable. CIMA® advisors are also 20% more likely to work with ultra-high-net-worth clients.
CFA® for advanced investment analysis
The Chartered Financial Analyst® (CFA®) program suits you if you want deeper investment analysis and portfolio management skills. It includes three exams and a demanding study plan. Sources cite 700–950 study hours and substantial work experience, with requirements described as three or four years. Check current rules before you enroll.
Choose practice-building, tax, and wealth specialties
Your next step may focus on growing a practice or adding tax knowledge. Compare each path with the work you want to do and the clients you hope to serve.
FSCP® for business development and client relationships
FSCP® builds product knowledge, prospecting, marketing, and business planning skills. Its five-course program has no prerequisites and may take four months. You need at least 70% on each final exam. Sixty-nine percent of designees report better client conversations, and they report 129% higher client retention than peers without a designation.
“Strong client relationships grow from useful conversations and steady service.”
CPA and PFS™ credentials for tax-aware financial planning
Requirements for a certified public accountant (CPA) vary by state. A common path includes a bachelor’s degree, 150 education hours, four exam sections, and one year of verified experience. Public accountants with planning skills may pursue PFS™, which requires a separate exam and two years of experience. The College’s TPCP® offers another tax planning option for finance professionals.
| Path | Key requirements | Career focus |
|---|---|---|
| FSCP® | Five courses; 70% per final | Business growth and client service |
| CPA | State rules; education and work experience | Accounting and tax knowledge |
| PFS™ or TPCP® | PFS™ exam and two years of planning experience | Tax-aware planning |
Pursue niche designations for specific client needs
A chartered financial professional may add a focused credential when a client’s needs go beyond routine planning. These paths can support your broader knowledge when life brings divorce, insurance questions, estate concerns, or fiduciary duties.
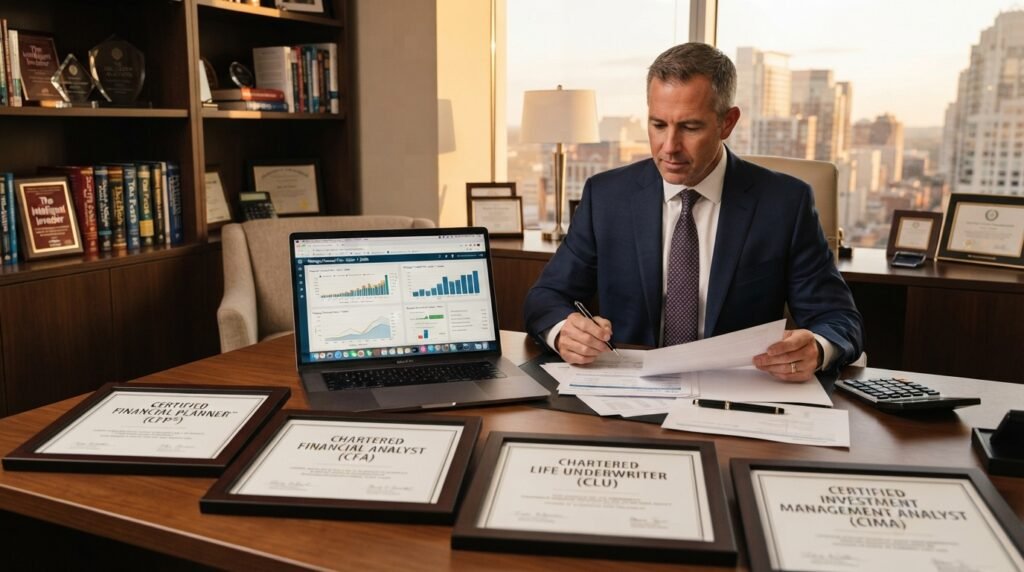
CDFA®, CLU®, and AIF® for specialized advice
CDFA® training covers the money issues that can arise during divorce. Topics include property division, retirement plans, tax, and insurance. The path calls for two years of financial or legal experience.
For life insurance and estate planning, CLU® coursework includes five core courses, three electives, and eight examinations. AIF® training focuses on fiduciary care through Fi360’s ethics and fiduciary-services course. Candidates pass an exam and complete six continuing-education hours each year.
Each certification serves a distinct need. Compare its focus with your current skills before choosing a designation. This can help you add useful knowledge in risk management, investment oversight, or fiduciary management without losing sight of your clients’ goals.
| Designation | Core focus | Key requirement |
|---|---|---|
| CDFA® | Divorce-related finances | Two years of relevant experience |
| CLU® | Life insurance and estate planning | Five core courses, three electives, eight examinations |
| AIF® | Fiduciary practices | Fi360 course, exam, and annual education |
Compare education, exams, and work experience requirements
Program rules can affect how soon you qualify and how much study you need. Check degree, course, exam, ethics, and ongoing learning rules before you choose. For more career credential resources, compare each path with the work you hope to do.
Review degree, coursework, and exam requirements
CFP® certification requires a degree, a CFP Board Registered Program, an exam, relevant experience, and an ethics commitment. ChFC® has no bachelor’s degree rule for enrollment, and its education can meet the CFP® exam education requirement. The American College offers both paths.
Study formats vary. CIMA® includes 250 coursework hours and two exams. FSCP® has five courses, no prerequisites, and a 70% passing score on each final. CFA® requires three exams and extensive study in areas such as risk management, portfolio management, and behavioral finance.
Account for experience and continuing education
CFP® professionals complete 30 continuing-education hours every two years. CFA® experience rules cite either 4,000 work hours over at least three years or four years of relevant experience. CIMA® calls for three years of industry experience. These standards build knowledge for planning, investment management, tax, and business needs.
Compare the full commitment before choosing a certification or designation. A useful overview of investment and management paths can also help you assess fit with clients.
| Credential | Study and exam structure | Degree or experience details |
|---|---|---|
| CFP® | Registered education program and exam | Degree, relevant experience, ethics, and ongoing education |
| ChFC® | Coursework can meet CFP® exam education rules | No bachelor’s degree needed to enroll |
| CIMA® | 250 coursework hours and two exams | Three years of industry experience |
| FSCP® | Five courses; 70% on each final | No prerequisites |
Match your certification to your clients and career goals
Start with the households you hope to serve and the work you want to do. Then compare broad financial planning, portfolio work, tax support, and practice growth. Your skills, experience, business model, and study time can help narrow the options.
If you want comprehensive advice, CFP® certification or the Chartered Financial Consultant (ChFC®) route may fit. The American College reports that ChFC® designees see 75% higher client-retention growth and 32% higher earnings growth than peers without a designation. These figures show reported trends, not guaranteed results.
For portfolio depth, WMCP® can build wealth management and investment management skills. Designees report 32% higher earnings growth, 28% higher client-number growth, and 144% higher retention growth. CIMA® (Certified Investment Management Analyst) may suit advisors who serve affluent households. The Investments and Wealth Institute reports a 20% greater likelihood of serving ultra-high-net-worth clients among CIMA® advisors.
Tax credentials, retirement study, and practice courses may also support your goals. A certified public accountant can bring tax knowledge, while a public accountant may consider planning credentials. Review each exam, education rule, and certification requirement in light of your experience.
The CFP Board’s public campaign stresses clients’ best interests and offers a website to find a CFP® professional. Choose a designation that strengthens your service, not just your title.
Conclusion
Choose a credential that fits your work today and builds skills for the clients you want to serve. Consider your goals, study time, and the needs of each client before you commit.
Series 65 can lead to fee-based investment advice, but it is a license, not a broad planning designation. CFP® and ChFC® suit broad planning paths. WMCP®, CIMA®, and CFA® offer distinct investment and portfolio management focuses.
FSCP®, CPA, PFS™, CDFA®, CLU®, and AIF® can support business growth, tax work, divorce, insurance, or fiduciary duties. Before you enroll, check degree rules, coursework, exams, experience, and continuing education. The right certification is one that fits your career goals and available time. Each chartered financial professional can use these factors to choose a practical next step.

