An investment gain is an increase in an asset’s value. You usually face a federal bill only after you sell for more than you paid. A rise on paper alone generally does not count as realized.
Your taxable income, filing status, asset type, and holding period all shape what you may owe. Rules can also vary by asset, so a stock sale may not follow the same path as a home or digital asset.
Timing matters. If you own an asset for one year or less, your profit generally faces short-term rates. Keep it for more than one year, and it may qualify for long-term rates. Your exact rate depends on your full financial picture.
A few steps may help you plan ahead. Loss harvesting, special accounts, charitable gifts, and a longer holding period may lower the amount due. This beginner’s guide explains how to calculate a gain, prepare common IRS forms, check asset-specific rules, and weigh your choices before a sale.
Key Takeaways
- A sale usually turns a paper rise into a realized profit.
- Your income, filing status, asset type, and holding period can affect your bill.
- Short-term and long-term holding periods may lead to different rates.
- Loss harvesting, special accounts, and charitable gifts may help you plan.
- Check IRS forms and asset rules before you sell or file.
What Counts as an Investment Gain?
A capital gain is the profit you make when you sell a capital asset for more than its cost basis. A price increase alone does not create a realized gain. In most cases, a sale must take place before you may owe capital gains tax.
Assets That May Create Taxable Gains
Many asset types can produce a profit. Examples include stocks, ETFs, mutual funds, bonds, real estate, cryptocurrency, and collectibles such as art, jewelry, coins, and antiques. Rules can differ by asset, so a stock sale may not follow the same path as a home sale.
Keep records showing what you paid and any later basis changes. These details help you work out your profit and report it correctly.
How Investment Funds Can Pass Gains to You
A mutual fund or ETF may sell securities in its portfolio for more than it paid. It can then pass capital gains to shareholders as a distribution. You may receive this investment income even if you did not sell your fund shares. The distribution may count as taxable income for the year, so review fund statements and tax forms when they arrive.
Tax implications of investment gains and when taxes apply
A change in a quoted price does not usually create a bill. A sale that leaves you with a profit can make the gain taxable. The amount depends on your cost basis, not just the price you received. Keep purchase records so you can work out the result.
When a Gain Becomes Taxable
Your holding period helps determine how the profit gets treated. A sale after one year or less may create short-term capital gains, which generally face ordinary income rates. If you hold an asset for more than one year, long-term rules may apply. Your income and filing status help set the applicable rate.
Report a realized gain on the return for the year you sold the asset. For example, a stock sold in 2026 generally belongs on your 2026 return. A mutual fund may also send you a taxable distribution, even when you keep your shares.
- Paper price changes usually do not trigger a filing event.
- Cost basis helps determine your actual profit.
- Fund distributions may count even without a share sale.
Check your records and fund statements before filing. The sale date and basis can both affect your final amount.
Realized Gains, Unrealized Gains, and Investment Losses
Your account can show a profit before you sell. That paper rise differs from a realized result, which usually follows a sale or a fund distribution.
Why You Generally Don’t Pay Tax on Paper Gains
If you buy a share for $10 and it later reaches $12, you have a $2 unrealized gain. While you hold it, that increase generally stays outside your tax calculation. Sell the share, and the realized profit may count in that year’s taxable income.
“A paper profit is not the same as cash from a sale.”
How Capital Losses May Offset Gains
Sell an asset for less than its adjusted basis, and you may have a capital loss. Under applicable rules, realized losses can offset realized profits. Tax-loss harvesting uses selected sales to help manage this net result.
Fund shares have a key exception: a mutual fund or ETF can sell assets inside its portfolio and pass taxable capital-gain distributions to you, even when you keep your shares.
| Situation | What happens | Possible tax treatment |
|---|---|---|
| Share rises from $10 to $12 | $2 unrealized gain | Generally not counted while held |
| Appreciated share is sold | Profit becomes realized | May enter your tax calculation |
| Asset sells below adjusted basis | Realized capital loss | May offset realized profits |
How to Calculate Your Taxable Capital Gain
Your calculation starts with the money a sale brings in and what you paid for the asset. Fees and basis changes can shift the result, so check your trade records before reporting a capital gain. These steps help you estimate your capital gains tax.
Determine Your Sale Proceeds
Start with the gross sale price, then subtract selling costs such as broker commissions and transaction fees. This gives you net proceeds from the sale.
Find Your Original or Adjusted Cost Basis
Your original cost basis usually includes the purchase price plus buying commissions and fees. Adjusted basis may change after reinvested dividends, wash sales, mergers, spin-offs, or stock splits. Keep records that explain each change.
Subtract Your Basis From Your Proceeds
For example, 100 shares bought at $50 cost $5,000. Selling them at $75 brings $7,500 in gross proceeds. Subtract the $5,000 basis from $7,500: the capital gain is $2,500 before fees or adjustments. Your taxable amount may differ once those items are included.
| Calculation step | Example amount | What it shows |
|---|---|---|
| Gross sale price | $7,500 | 100 shares sold at $75 each |
| Purchase cost basis | $5,000 | 100 shares bought at $50 each |
| Preliminary gain | $2,500 | Proceeds minus purchase basis, before fees or adjustments |
Short-Term and Long-Term Capital Gains
The time you hold an asset can change how the IRS treats your profit. The key date is when you sell, so check it against your purchase date before you estimate what you may owe.
How Your Holding Period Affects Your Tax Rate
An asset held for more than one year may qualify for long-term capital gains rates. For federal purposes, those rates are generally 0%, 15%, or 20%, based on your taxable income. An asset held for one year or less creates short-term capital gains, which generally use ordinary income tax rates.
Why Short-Term Gains Are Taxed as Ordinary Income
Short-term profit is usually added to your ordinary income. That means your income tax rate can matter more than a special long-term rate. For example, a $10,000 gain at a 15% long-term rate means $1,500 in tax. At a 24% ordinary rate, the same short-term profit means $2,400.
Confirm both dates before you sell. Crossing the one-year mark may change the rate applied to your money. Your actual bill also depends on taxable income and other rules, so check current IRS guidance before filing.
Current Long-Term Capital Gains Tax Rates by Filing Status
Federal rates depend on your taxable income and filing status. They use income thresholds, not one flat rate for every filer or every dollar. Your profit may fall into more than one bracket.
How Taxable Income Affects Your Rate
For 2025, single filers reach the 0% threshold at $48,350. In 2026, that threshold rises to $49,450. Married couples filing jointly have a 2026 threshold of $98,900, while the 20% bracket starts above $613,700.
Other 2026 examples include $66,200 for head-of-household filers and $49,450 for married filing separately. These long-term capital gains thresholds use taxable income. Short-term capital gains generally follow ordinary income tax rates instead. Your state may also charge tax, creating a separate amount due.
| Filing status | Year | Threshold or bracket detail |
|---|---|---|
| Single | 2025 | 0% through $48,350 |
| Single | 2026 | 0% through $49,450; 20% above $545,500 |
| Married filing jointly | 2025 | 0% through $96,700 |
| Married filing jointly | 2026 | 0% through $98,900; 20% above $613,700 |
| Head of household | 2026 | 0% through $66,200 |
| Married filing separately | 2026 | 0% through $49,450 |
How Dividends, Interest, and Fund Distributions Are Taxed
Payments from stocks, bonds, and funds can add to your yearly income, even when you do not sell shares. The rules depend on the type of payment.
Ordinary and Qualified Dividends
Ordinary dividends generally use ordinary income tax rates. Qualified dividends may get lower long-term capital gains rates if they meet IRS rules. Check Form 1099-DIV: box 1 usually lists ordinary dividends, while box 1b reports qualified dividends.
A fund distribution can affect your return even if you keep your shares. A fund may pay you after selling stocks or other assets in its portfolio.
Taxable and Tax-Exempt Interest
Interest from many bonds and savings accounts is generally taxed at ordinary income rates. Some payments may be exempt from federal tax. Examples include municipal bond interest, private activity bond interest, and exempt-interest dividends. Exempt status may not cover every state or federal rule, so check your statement.
Keep these forms with your records. They help you report the right amount and sort taxable income from exempt income.
Additional Taxes on Investment Income
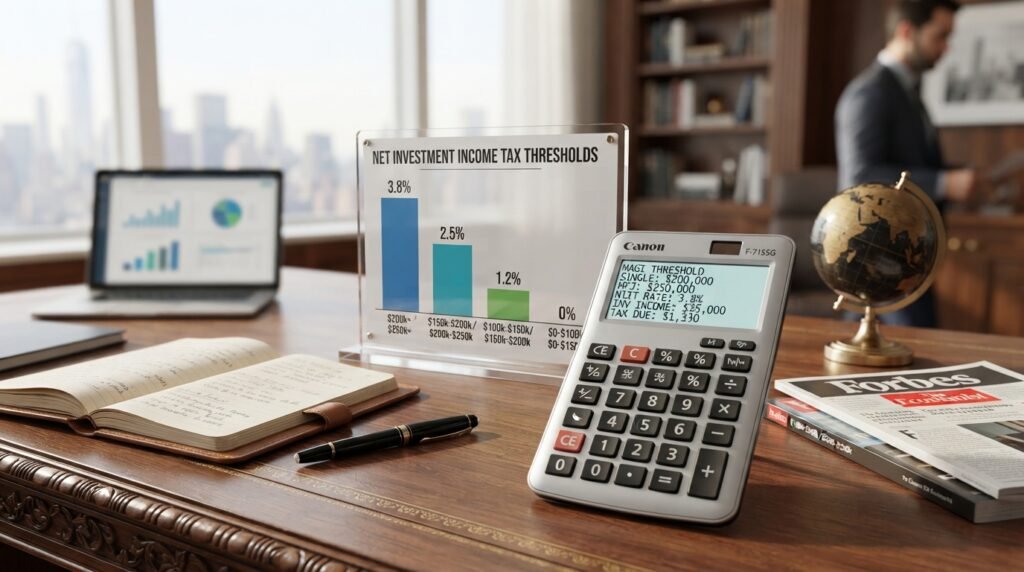
Some households may owe a second federal charge on certain earnings. The Net Investment Income Tax (NIIT) is an additional 3.8% tax that may apply when your modified adjusted gross income (MAGI) exceeds a set limit.
When the Net Investment Income Tax May Apply
Your filing status sets the MAGI threshold. However, passing that limit alone does not mean you owe NIIT. Your income source also matters, and the calculation may depend on your full return.
Potentially covered sources include interest, dividends, capital gains, rent, royalties, and nonqualified annuity distributions. These amounts may face NIIT even when they already count as ordinary income. The charge can apply alongside capital gains tax, so your final rate may differ from the rate on a sale alone.
Review both your MAGI and income sources. Check current IRS guidance or speak with a tax professional to assess your situation and any loss offsets.
| Filing status | MAGI threshold | Potential NIIT rate |
|---|---|---|
| Single | More than $200,000 | 3.8% on eligible income |
| Married filing jointly | More than $250,000 | 3.8% on eligible income |
| Married filing separately | More than $125,000 | 3.8% on eligible income |
Tax Forms and Records to Keep for Your Investments
Your brokerage forms offer a starting point, but they may not show every basis change. Compare each form with your records before you file.
Understanding Forms 1099-B, 1099-DIV, and 1099-INT
Form 1099-B reports proceeds from selling stocks and other investments, and may show cost basis. Form 1099-DIV lists dividends and fund distributions. Form 1099-INT commonly reports interest from a bank or brokerage account. These forms help track investment income.
“Match each reported amount with a record you can verify.”
Tracking Cost Basis Adjustments and Transaction Fees
Trade confirmations can fill gaps. Check purchase fees, sale costs, and reinvested dividends against each form. Wash sales, mergers, spin-offs, and stock splits may change your original basis. Save statements that explain each adjustment.
- Keep trade confirmations and account statements.
- Record fees and reinvested dividends.
- Note corporate actions that affect basis.
Financial firms generally post 1099 forms by late January. Partnership K-1 forms often arrive by mid-March. Keep these records with your annual files, including those tied to a retirement account.
Special Tax Rules for Homes, Inherited Assets, and Other Investments
Some asset sales follow special federal rules, so check your eligibility before you report a profit. A home sale, an inheritance, and certain securities may receive different treatment under the capital gains tax rules.
The Primary Residence Gain Exclusion
If you sell your primary home, you may exclude up to $250,000 in profit as an individual. A married couple filing jointly may qualify to exclude up to $500,000. You generally must own and use the home as your main residence for at least two years during the five years before the sale.
Stepped-Up Basis for Inherited Investments
An inherited asset may receive a basis equal to its fair market value at the original owner’s death. This adjustment can reduce the amount counted as profit when you later sell. Keep records that support the value and date.
Rules for Small Business Stock and Municipal Bonds
Qualified small business stock held for at least five years may qualify for a gain exclusion under current rules. Municipal bond interest is different: it may be exempt from federal tax, but that is not a stock-sale exclusion. Check eligibility, holding periods, and state treatment before acting.
Ways to Plan for and Potentially Reduce Your Tax Bill
Good timing and account choices may help you keep more from a sale. Review your goals, income, and holding period before you act.
Tax-Loss Harvesting and Gain Harvesting
Selling an asset below its adjusted basis may create a realized loss that offsets taxable profits. Still, each sale should fit your broader financial plan, not just lower a bill.
You may also sell appreciated shares when you qualify for a 0% long-term capital gains rate. This approach can reset your basis, but check your income first.
Holding Assets Longer and Choosing Accounts
Keeping an asset for more than one year may qualify its profit for long-term rather than short-term treatment. Traditional IRAs and 401(k)s generally defer current tax. Qualified Roth, HSA, and 529 plan withdrawals may be tax-free when you meet the rules.
Donating Appreciated Assets and Checking State Rules
Donating appreciated shares may support a charity and reduce the need to sell them yourself. State rules can differ from federal rules, so check both before acting.
A qualified opportunity fund may offer specified benefits when you invest within 180 days after a gain and hold for at least five years. Review its terms with a tax professional.
Conclusion
Before you place a sell order, check what it may mean for your return. A paper rise, such as a share moving from $10 to $12, usually is not taxable by itself. Selling above adjusted basis generally realizes capital gains.
Hold an asset for more than one year, and long-term rates may apply. A year or less usually brings ordinary-income treatment. Your income and income tax rate help shape the final amount.
Keep records for purchase costs, fees, reinvested dividends, and later basis changes. They help show the right gain or loss. Review Forms 1099-B, 1099-DIV, and 1099-INT with your investment account statements.
Before selling, weigh losses, account types, charitable gifts, and federal and state rules. A short review can help you plan for capital gains taxes and avoid surprises. For complex decisions, consult a qualified professional.
FAQ
What determines your long-term capital gains rate?
How does your holding period affect the rate?
Do you owe money when your stock price rises but you keep the shares?
Can an investment loss lower the amount you owe?
FAQ
What determines your long-term capital gains rate?
Your taxable income and filing status help set your rate. For married filing jointly, the income thresholds differ from those for single filers. Check the limits for the year you sell an asset.
How does your holding period affect the rate?
If you own an asset for more than one year, a lower long-term rate may apply. A sale after one year or less usually counts as short-term and is taxed like ordinary income.
Do you owe money when your stock price rises but you keep the shares?
Usually, no. An increase in value is an unrealized profit. You generally report it only after you sell or exchange the asset.
Can an investment loss lower the amount you owe?
Yes. A capital loss can offset capital gains. If your losses exceed your gains, you may be able to deduct up to ,000 against ordinary income each year, or
FAQ
What determines your long-term capital gains rate?
Your taxable income and filing status help set your rate. For married filing jointly, the income thresholds differ from those for single filers. Check the limits for the year you sell an asset.
How does your holding period affect the rate?
If you own an asset for more than one year, a lower long-term rate may apply. A sale after one year or less usually counts as short-term and is taxed like ordinary income.
Do you owe money when your stock price rises but you keep the shares?
Usually, no. An increase in value is an unrealized profit. You generally report it only after you sell or exchange the asset.
Can an investment loss lower the amount you owe?
Yes. A capital loss can offset capital gains. If your losses exceed your gains, you may be able to deduct up to $3,000 against ordinary income each year, or $1,500 if you file separately. You can generally carry unused losses forward.
When might the net investment income tax apply?
You may owe this 3.8% levy if your modified adjusted gross income exceeds $200,000 as a single filer or $250,000 if married filing jointly. It applies to the lesser amount: your net investment income or the amount above your threshold.
How are dividends and interest treated?
Qualified dividends may receive long-term rates, while ordinary dividends usually count as ordinary income. Bank interest is generally taxable; interest from some municipal bonds may be exempt from federal income tax.
Which records should you keep after selling an asset?
Save Forms 1099-B, 1099-DIV, and 1099-INT, plus trade confirmations and basis records. Include purchase costs, fees, and any basis adjustments so you can check your reported profit or loss.
Does inheriting an asset change its cost basis?
Often, an inherited asset receives a basis tied to its fair market value on the prior owner’s date of death. Special rules and exceptions may apply, so check the estate records before you sell.
,500 if you file separately. You can generally carry unused losses forward.
When might the net investment income tax apply?
You may owe this 3.8% levy if your modified adjusted gross income exceeds 0,000 as a single filer or 0,000 if married filing jointly. It applies to the lesser amount: your net investment income or the amount above your threshold.
How are dividends and interest treated?
Qualified dividends may receive long-term rates, while ordinary dividends usually count as ordinary income. Bank interest is generally taxable; interest from some municipal bonds may be exempt from federal income tax.
Which records should you keep after selling an asset?
Save Forms 1099-B, 1099-DIV, and 1099-INT, plus trade confirmations and basis records. Include purchase costs, fees, and any basis adjustments so you can check your reported profit or loss.
Does inheriting an asset change its cost basis?
Often, an inherited asset receives a basis tied to its fair market value on the prior owner’s date of death. Special rules and exceptions may apply, so check the estate records before you sell.