
Investing means making choices while outcomes remain uncertain. Every investment can rise or fall, so your plan should connect possible returns with the amount of loss you can accept. The aim is not to predict every move. It is to make choices that fit your goals.
Two classic tools explain this tradeoff: mean-variance portfolio optimization and the capital asset pricing model. Both link expected returns with risk, though each frames that link differently. These ideas can help you judge performance rather than chase every market swing.
You cannot remove uncertainty from investing. A practical approach starts with knowing what you own and how much loss your budget can absorb. Avantis Investors’ article, dated 06/10/2025, highlights why a clear process matters.
Assess your comfort with possible losses, then shape your portfolio around your time horizon and financial goals. Effective planning does not mean avoiding market exposure; it means choosing it with care and knowing how it may affect your money. This guide covers measurement, diversification, allocation, and regular review as connected steps. You will build a strategy that suits your needs and supports choices through changing conditions.
Key Takeaways
- You cannot remove uncertainty, but you can choose how much loss you can accept.
- Classic frameworks show how possible returns relate to risk.
- Your time horizon and financial goals can guide portfolio choices.
- Diversification and allocation help shape your approach to market exposure.
- Regular reviews help you adjust your plan as your needs change.
What Investment Risk Means for Your Portfolio
Investment risk is the chance of a financial loss or a return that differs from what you expect. All investing carries some risk, even when past results look strong. A record of gains cannot make future outcomes certain.
Risk as the possibility of loss and uncertain returns
Your portfolio risk depends on how its holdings may respond to changing conditions. Mean-variance portfolio optimization and the capital asset pricing model both link risk with expected return. These early modern portfolio theory tools help explain why greater potential returns often come with greater uncertainty.
Why uncertainty cannot be removed entirely
You cannot remove every risk from an investment. Avoiding all market exposure may also limit growth. For example, investors who sell during a downturn may miss a recovery, while volatility continues to affect prices.
Risk management means shaping exposure, not erasing uncertainty. A clear process helps you weigh possible outcomes, consider the time you have, and decide which risks fit your goals. This approach can make portfolio choices more deliberate without promising a certain result.
Why Risk Management Matters to Your Financial Goals
Your financial goals shape how much uncertainty may suit your plan. Portfolio models, including mean-variance optimization and the capital asset pricing model, link investment return with risk. A higher level of risk can bring a wider range of possible returns, both up and down.
Balance potential returns with the risks you take
A growth-focused plan may accept more market swings. A plan centered on preserving capital may favor steadier choices, especially when you need the money soon. Your goals, time horizon, and tolerance for loss can help guide that balance.
Sound risk management can improve the chance of preferred results, but it cannot promise a specific outcome. Businesses choose which risks merit resources, and investors can use the same deliberate approach. Consider your return needs before making investment decisions.
“A clear plan guides your choices, even when markets change.”
For each business, resource choices reflect its aims and limits. For your portfolio, compare possible gains with the uncertainty you can accept. Thoughtful investing connects each choice to your goals rather than a short-term market move.
Risk management in investments: Build a Strategy Around Your Needs
Your plan works best when each holding has a clear purpose. Risk management gives you a repeatable way to connect your choices with your goals. It also helps you avoid relying on one risk level that may not fit every investor.
Start with a simple process: define your aims, spot possible exposures, decide what you can accept, then review your choices. Measure each exposure and compare it with your objectives. This can help you make more informed decisions as your needs change.
Each investment should work with the rest of your portfolio. A holding may support growth, add stability, or provide access to cash. Together, your selections should reflect your circumstances, not just a target return. These strategies can make your broader plan easier to follow.
Your time horizon, financial capacity, and tolerance for volatility all matter. Those factors help set an approach that feels both practical and sustainable. The next step is to consider how your goals and timeline shape that approach.
| Step | Purpose | Example question |
|---|---|---|
| Identify | Clarify your objectives | What do you want your money to do? |
| Measure | Gauge possible exposure | How much fluctuation can you accept? |
| Align | Match choices with goals | Does each holding serve a purpose? |
Set Financial Goals and Choose Your Time Horizon
A calendar can be as useful as a balance sheet when you shape a portfolio. Name each goal, the date you may need the money, and the amount required. A longer time horizon gives investors more time to recover after market drops, though it cannot ensure gains. Your schedule helps set a suitable level of risk.
Adjust Your Investment Approach as Your Goals Get Closer
A target several years away may call for a different investment mix than an upcoming retirement or other near-term need. As the date gets closer, many investors aim for less risk. Ask whether your plan still fits expected returns and planned withdrawals. As an investor, let your needs guide each choice.
Keep money meant for long-term growth apart from funds you may need soon for expenses or income. This can reduce pressure to sell assets at a poor price. Risk management links each choice with its purpose; it does not promise a return.
Review goals each year and after major life changes. If your plans shift, update near-term reserves and reassess investment choices. Check the time available, too, so your investing approach stays suited to your needs.
Assess Your Risk Tolerance and Capacity for Loss
Your comfort with uncertainty and your ability to absorb a setback are not the same. Risk management starts by separating what you are willing to face from what your finances can support.
Consider both your comfort with volatility and financial circumstances
Your risk tolerance reflects how much fluctuation you can accept without making rushed decisions. Your income, savings, bills, and time horizon show how much loss your plans can handle. These factors help you choose an investment mix that fits your life.
- Check your budget: Could a drop affect bills or planned spending?
- Consider your comfort: An allocation that keeps you up at night may be hard to stick with through market swings.
- Weigh both sides: Avoiding nearly all uncertainty may slow progress toward goals, while too much exposure can strain your finances.
Your needs can shift after a job change, a new expense, or a move closer to a goal. Investors benefit from reassessing their choices when life changes, rather than assuming their preferred level stays fixed. For help reviewing your approach, contact a financial advisor.
Identify the Main Risks That Can Affect Your Investments
Several forces can affect what your portfolio is worth. Knowing their sources helps you choose strategies that fit your goals and your ability to handle change.
Market risk and changing economic conditions
Market risk is the chance that economic news, headlines, or geopolitical events will lower asset values. This exposure can affect business holdings and securities across markets.
Inflation risk and the loss of purchasing power
When prices rise faster than your returns, your money buys less. This can weaken the value of income from bonds and other holdings over time.
Interest rate risk and credit or default risk
Bond prices generally move opposite interest rates. Longer-maturity bonds may react more sharply when rates change. Credit risk is the chance an issuer cannot repay its loan or make interest payments. BBB or higher ratings count as investment grade and signal the issuer’s financial strength and ability to pay on time.
These factors can touch income-producing securities, business holdings, and property. Risk management starts with knowing which exposures matter most to your plan.
| Exposure | Main cause | Possible portfolio effect |
|---|---|---|
| Market | Economic or geopolitical events | Asset values may fall |
| Inflation | Prices rise faster than returns | Purchasing power may decline |
| Interest and credit | Rate changes or issuer trouble | Bond prices or payments may weaken |
Understand Portfolio Concentration and Investment Correlations
A portfolio can look varied while its holdings still depend on the same forces. Concentration grows when you place much of your savings with one asset class or a single stock. A sharp price drop there may cause a large loss.
Different labels do not always mean different behavior. During market stress, high-yield bonds can move alongside equities. That link may make them an unreliable hedge when stocks fall. Holdings that share industries, markets, or property exposure may also move together, adding volatility rather than balance.
For sound risk management, look through mutual funds and ETFs to their underlying securities. Check for overlap across funds, sectors, and property holdings. This review can show whether you have access to varied assets or repeated exposure. Diversification can reduce portfolio risk from concentration, but it cannot assure profit or prevent principal losses.
| What to check | Why it matters | Example |
|---|---|---|
| Concentration | A large holding can magnify losses | One stock or asset class |
| Shared movement | Similar holdings may fall together | High-yield bonds and equities |
| Fund overlap | Repeated holdings limit variety | Same securities across funds |
Measure Portfolio Risk With Quantitative Tools
Numbers can help you compare possible swings, but no single measure tells the whole story. Use them as part of your review process, alongside your goals and risk tolerance.
Standard deviation and the spread of investment returns
Standard deviation shows how widely returns vary around an average. A higher figure often signals greater volatility, while a lower one points to narrower swings. This measure can help you compare securities, a fund, or investment choices, but past patterns do not predict future performance.
Beta and sensitivity to market movements
Beta measures how a portfolio or fund responds to market movements. A beta above one suggests larger swings than the market; below one suggests smaller ones. Beta offers one useful view, not a complete risk assessment.
Value at risk and potential losses over a set period
Value at risk (VaR) estimates a potential worst loss over a defined time and confidence level. It is not a guarantee or a cap; actual losses may exceed the estimate.
Compare these measures, then add a qualitative review. Consider your holdings, goals, and comfort with possible losses. This balanced process helps you judge whether your portfolio’s level of exposure fits your needs.
Evaluate Investments With Due Diligence and Holdings Analysis
A fund’s recent returns show what happened, not every exposure you own today. Holdings can change, while past performance may hide new business or market factors. Review current positions before you judge an investment’s fit.
Look beyond past performance to underlying securities
Holdings-based analysis checks the securities and assets a portfolio owns now. It can help you see what may cause a position to gain or lose value. Use this review alongside returns-based measures for a fuller view of risk and performance.
Before choosing a fund, do careful due diligence. Check its holdings, business exposures, and role within your portfolio. Also compare positions across funds. Overlap may create exposure you did not intend, even when each fund follows a different strategy.
- Review current securities and major holdings.
- Note shared issuers, sectors, and risk factors.
- Ask how each position supports your goals.
This process supports clearer decisions. It also helps you judge whether your risk management approach still matches the assets you own.
| Review area | What to check | Why it matters |
|---|---|---|
| Holdings | Current securities and issuers | Shows present exposures |
| Fund overlap | Repeated positions across funds | May reveal hidden concentration |
| Portfolio role | Fit with goals and time horizon | Connects each choice to your plan |
Diversify Across Asset Classes, Industries, and Geographies
A broad mix can help keep one setback from shaping your entire financial plan. Diversification spreads investments across asset classes, industries, and regions. It also forms a foundation for risk management.
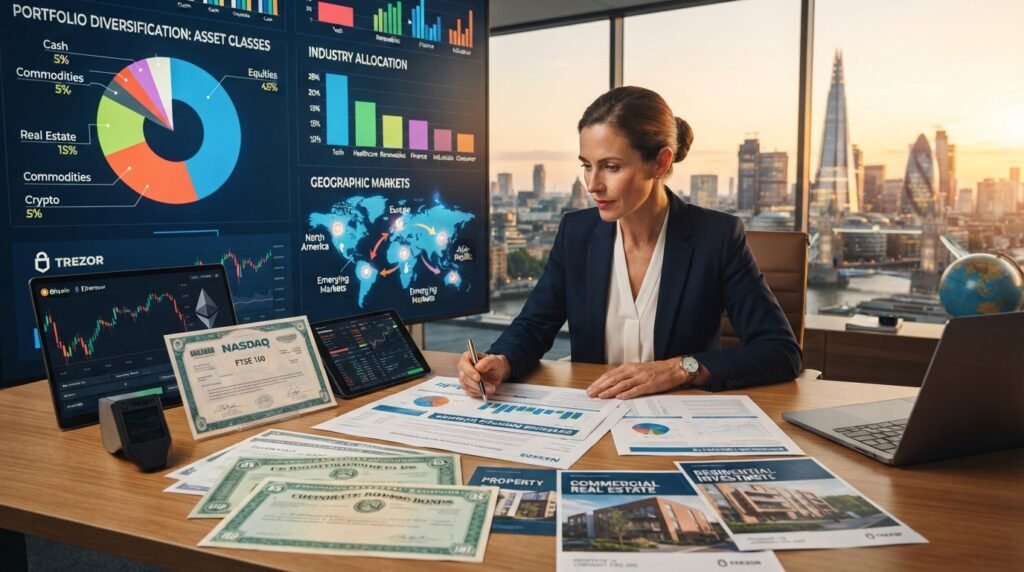
Holdings may react differently as markets shift. Gains from one area may help offset weaker results elsewhere. This approach can reduce reliance on a single market, industry, or type of asset, though it cannot remove every risk.
Review stocks, bonds, funds, securities, and property-related exposure across your portfolio. Look for repeated holdings or shared risks, not just different fund names. A varied mix may provide access to more markets, but it does not assure profit or protect against loss of principal.
Diversification helps shape exposure; it cannot prevent losses. Your investment strategy should reflect your goals and comfort with volatility. The right mix depends on what you need your assets to do and when you may need them.
| Area to review | What to check | Purpose |
|---|---|---|
| Asset classes | Stocks, bonds, and property | Limit reliance on one type |
| Industries and regions | Shared market risk or exposure | Spread risks across sectors |
| Funds and securities | Repeated holdings | Spot hidden concentration |
Match Your Asset Allocation to Your Risk and Return Needs
Asset allocation is how you spread your portfolio across categories such as stocks, bonds, and cash. Your goals, time horizon, tolerance for loss, and need for income can guide that mix. Risk management connects your expected return with the uncertainty you accept.
Use a Benchmark to Check Your Allocation
Compare your portfolio with a benchmark that reflects your aims and time frame. If its mix takes far more risk than the benchmark, it may be too aggressive. A much steadier mix may be too conservative for your needs. Check the benchmark’s holdings, too; a fund with a different mix may not offer a fair comparison.
Mean-variance optimization and the capital asset pricing model link potential returns with risk. They offer a framework, not a promise of performance. Consider whether your investment mix can support your return needs and whether you can absorb losses. Your available capital also matters.
An investor may need a different level of exposure as circumstances shift. Investors can review the strategy when goals, income needs, or market conditions change. Treat the allocation as a working plan, not a permanent choice.
Manage Bond Risks With Credit Quality and Duration
Bonds can support portfolio income, but their value may change as interest rates and issuer finances shift. Duration and credit quality offer two useful ways to assess this risk. Consider both beside your goals, not as stand-alone signals.
Understand how bond prices may respond to interest rate changes
Duration estimates how sensitive a bond’s price is to interest rate moves. Longer-duration bonds usually change more when rates move. Bond prices generally fall when interest rates rise and may rise when rates fall. Still, bond values fluctuate for other reasons, so this pattern cannot prevent losses.
Weigh credit quality against yield potential
Credit ratings—from AAA to D—indicate an issuer’s financial strength and ability to make timely interest payments. Bonds rated BBB or higher are investment grade. They generally carry less default risk, though they often offer lower yield potential than weaker-rated issues.
Compare each bond or bond fund with your full portfolio. Check its income role, possible overlap with other securities, and fit beside stocks, funds, and property. This risk management review can help you judge whether the added risk suits your plans.
Address Inflation, Sequence-of-Returns, and Longevity Risks
Retirement changes how a portfolio responds to market swings. The timing of gains and losses matters more as you near withdrawals.
How return timing affects retirement withdrawals
Sequence-of-returns risk describes how the order of gains and losses affects savings. A sharp drop close to retirement can be harder to recover from once you start taking money out. You may sell assets to cover expenses, leaving fewer shares to benefit from a rebound. Investors still adding money have more time to wait through a downturn, so this timing risk can matter less for them.
Inflation also weakens purchasing power when returns fail to keep pace with rising prices. Over time, that can reduce what your savings can buy.
Plan for income across retirement
Longevity risk means you may outlive your savings. Plan for income across retirement, not only its early years. Your withdrawal pace, time horizon, and ability to handle volatility should shape how much growth your portfolio needs. Bonds may add income, while other investments can support long-term growth; neither removes risk or guarantees a return.
Set aside money for near-term needs, then review your investment mix against your financial goals. Sound risk management balances growth with planned withdrawals. This approach helps investors prepare for losses while keeping a chance to meet future costs.
Monitor Your Portfolio and Respond Thoughtfully to Volatility
Markets shift, and your goals or finances may change too. A planned review helps you respond with purpose instead of reacting to each price move. Strong risk management pairs clear data with personal judgment; neither offers the full picture.
Review Exposure as Your Needs Change
After a major market move or a life change, compare current holdings with your intended allocation. Check whether each fund still serves its purpose, whether exposures have shifted, and whether the portfolio’s value fits your plan. This helps you judge performance without treating one short-term return as a verdict.
- Use measures such as volatility alongside your goals and ability to stay invested.
- Review your investment choices on a schedule, and after meaningful changes.
- Adjust only when new facts support a change—not from a quick reaction.
Avantis Investors’ article, dated 06/10/2025, reminds you to match risk choices with your financial plan and capacity to stay invested. Financial professionals can also consult BlackRock specialists when assessing portfolio exposure. A disciplined review keeps decisions tied to what matters: your needs, your time horizon, and the role your money must play.
“A thoughtful review turns new information into a reasoned choice, not a reflex.”
Conclusion
No portfolio can promise a smooth path, but a clear process can help you stay focused. Mean-variance analysis and the capital asset pricing model connect potential returns with risk; neither predicts what comes next.
Build your approach around your goals, time horizon, finances, and tolerance for possible losses. Use diversification, careful research, and suitable measures to understand what you own. These tools can reveal exposure, yet no strategy removes uncertainty or guarantees gains.
Review your holdings when your circumstances change, and set a plan for market swings before they arrive. Risk management is an ongoing practice of deliberate choices that keeps your portfolio aligned with your financial goals. When conditions shift, pause, assess the facts, and act only when a change supports your plan.

