
Your retirement years can bring more choice, but they also raise practical questions: What lifestyle do you want, and can your savings, Social Security, and other sources support it? Start by naming your retirement goals and estimating the income you can expect.
Fidelity suggests saving 15% of your annual income, including any employer match. If that target feels out of reach, start with an amount you can manage. Starting now is better than waiting for the perfect time.
Your retirement plan can change as life does. Use a calculator to estimate how much money you may need, then track progress as your goals and needs shift. Review your investment mix and the benefits available to you, too.
Need expert input? SmartAsset’s free matching tool connects you with up to three vetted fiduciary advisors in your area. Its process takes just a few minutes and can help you find support with retirement planning.
Begin with a few clear steps: check your savings and expenses, consider tax effects, and note estate priorities. Adjust your plans over the years as your needs change.
Key Takeaways
- Define your preferred lifestyle and retirement goals.
- Include Social Security and other income sources in your estimate.
- Use Fidelity’s 15% savings guideline as a benchmark, not a reason to delay.
- Revisit your plan as goals, expenses, and needs change.
- SmartAsset can match you with up to three vetted fiduciary advisors.
Financial planning for retirees: Define your goals and retirement lifestyle
Begin with a picture of the life you want. Your retirement goals may include a new place to live, more travel, favorite hobbies, or part-time work. Each choice can shape your expenses and daily routine. Clear goals give your retirement plan a useful direction.
Picture how you want to spend your retirement years
Fidelity’s benchmark suggests saving 10 times your annual salary by age 67. Use it as one reference, not a rule. Your timeline, savings, and retirement goals matter more. Social Security may start at 62, but an early claim lowers your benefit. Full retirement age is usually 66 or 67, based on your birth year. Waiting until 70 may raise benefits to as much as 132% of the standard amount.
Account for family support, debt, and legacy goals
Include debt, family support, and any legacy wishes in your strategy. Consider how long you may be living in retirement and whether you might provide care or money to adult children or grandchildren. Review your accounts and track changes as your needs shift. A realistic plan connects your goals with the resources you have.
Estimate how much money you may need
An expense estimate turns long-term goals into a useful spending target. Start with costs you expect, then test how housing or health changes could affect your savings.
Build a budget around expected costs
List housing, food, transportation, tax, health care, travel, and personal expenses. A common target is annual income equal to 70%–80% of your pre-retirement income. Fidelity estimates savings may need to cover at least 45% after Social Security and pensions.
Your retirement plan should reflect your goals and lifestyle, not one savings target. Use these steps in retirement planning to see how much money you may need from savings.
- Check whether a move, mortgage payments, or rising living costs change your expected expenses.
- Fidelity’s 2026 estimate puts one 65-year-old’s health-care costs at $185,500 in after-tax savings.
- Compare income, accounts, and investments with your budget using a calculator. Adjust how much you need to save.
| Cost area | Items to estimate | Budget check |
|---|---|---|
| Housing | Rent or mortgage, upkeep | Include any loan balance |
| Daily costs | Food, transport, personal needs | Estimate monthly expenses |
| Health and travel | Care, premiums, trips | Review annual totals |
Map out your retirement income sources
List the payments and accounts you expect to use. Include Social Security benefits, pensions, annuities, and portfolio withdrawals. This gives you a clearer view of the money available to meet essential costs and your personal goals.
Combine benefits, pensions, and savings
Check your estimated Social Security benefit and any pension statements. The Social Security Administration says benefits can rise about 8% each year you delay claiming past full retirement age, up to age 70. If you may work part-time, weigh how your claiming age could affect your total income.
Compare predictable and market-based payments
Social Security, pensions, and some annuities can provide steady payments. Investment-based income may change with market returns. Fidelity notes that an income annuity may help cover essential expenses that other guaranteed sources do not meet. Compare each source with housing, food, insurance, and health-care costs to see how much your savings must provide.
- Separate predictable payments from variable investment withdrawals.
- Review how claiming choices affect your income retirement strategy.
- Match each source to the expenses it can cover.
| Income source | Payment pattern | Use in your estimate |
|---|---|---|
| Social Security | Monthly benefit | Check claiming age and estimate |
| Pension or annuity | Often predictable | Review payment terms |
| Investments | May vary by market | Estimate cautious withdrawals |
Choose retirement accounts and tax-smart savings options
The right mix of accounts can shape how much you keep and when you can use it. Compare workplace plans, IRAs, and health savings accounts before choosing where to add savings.
Review workplace plans, IRAs, and health savings accounts
Check fees, match rules, access limits, and tax treatment. An HSA may offer tax advantages when you meet its rules and use funds for eligible health costs.
Weigh tax treatment before you contribute
Traditional accounts may lower taxable income now, while qualified Roth withdrawals can be tax-free. Your current tax rate, future income, and savings goals can guide your choice. Review the rules before moving money.
“A useful account choice fits both your tax picture and your future needs.”
- In 2026, IRA limits are $7,500, plus $1,100 at age 50 or older, subject to rules.
- The 401(k) limit is $24,500. Catch-ups are $8,000, or $11,250 at ages 60–63 when allowed.
- HSA limits are $4,400 for individual coverage and $8,750 for family coverage, including employer deposits.
Under SECURE 2.0, certain higher earners must make 2026 401(k) catch-up contributions as Roth contributions.
| Account | 2026 limit | Key point |
|---|---|---|
| IRA | $7,500; $8,600 at age 50+ | Eligibility rules apply |
| 401(k) | $24,500; catch-ups may apply | Some catch-ups must be Roth |
| HSA | $4,400 individual; $8,750 family | Employer deposits count |
Create a sustainable withdrawal strategy
Your withdrawal choices can shape how long your savings last. Compare steady payments with regular expenses. Social Security or pension income may cover part of your needs, while savings and investment accounts can fill the gap. This gives your retirement plan a clear base without locking you into one fixed amount.
Set a flexible rate and plan for required distributions
Fidelity’s general guideline is to withdraw no more than 4%–5% of savings in your first retirement year. Then adjust the amount each year to account for inflation. Treat this as a starting point, not a guarantee. A flexible strategy can help your retirement income keep pace with changing costs.
- Use withdrawals to cover the gap between predictable income and expenses.
- Required minimum distributions (RMDs) generally start at age 73. The starting age is scheduled to rise to 75 in 2033.
- You may delay your first RMD until April 1 of the next year. That can mean two distributions in one year and a larger tax bill.
Review your retirement savings, account rules, and tax needs each year. Adjust withdrawals when health costs, market returns, or other expenses change. Your plan should adapt as life and income needs shift.
Align your investments with your time horizon
Set your investment mix by when you expect to use the money. Weigh your retirement goals, financial situation, and comfort with risk. Your retirement plan should balance growth potential with the need to access savings.
Fidelity’s hypothetical example assumes a 7% annual nominal return, with contributions made on January 1 through age 67. This rate is not guaranteed. Investments with the potential to earn that return can also lose value.
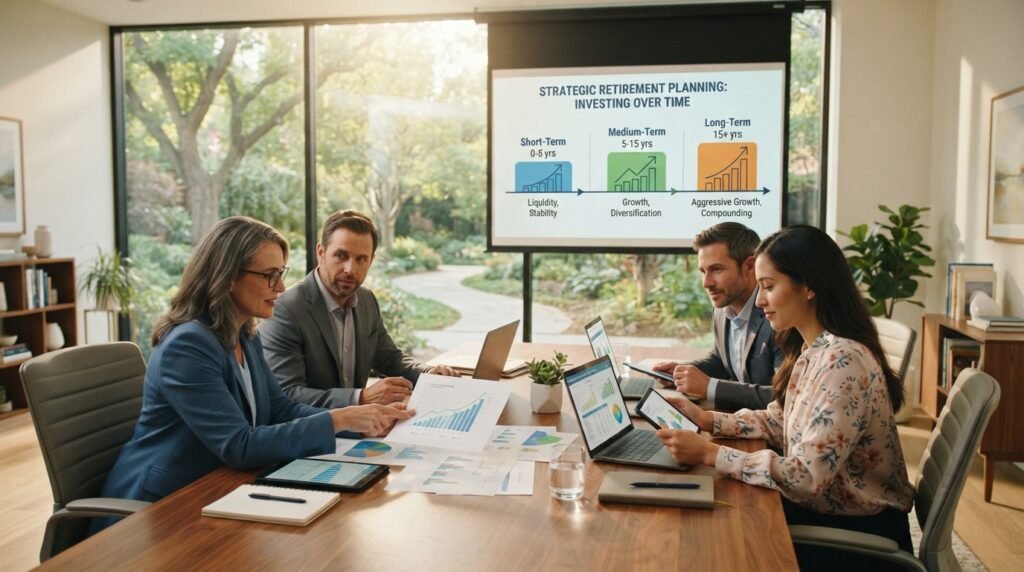
Diversify among stocks, bonds, and short-term investments. Different types can help balance growth and stability, rather than tying your savings to one investment. Match the mix to your expected income needs and the years until withdrawal.
Target-date funds offer a diversified approach. They gradually shift to a more conservative mix as the target date approaches and passes. Check whether that path fits your retirement savings and retirement accounts.
Review investments from time to time. Changes in spending, income, or goals may call for updates to your plan. A suitable mix can support your needs without relying on one investment.
| Investment type | Common role | Key consideration |
|---|---|---|
| Stocks | Growth potential | Values can rise or fall |
| Bonds | Income and balance | Prices and yields can change |
| Short-term investments | Stability and access | Returns may be lower |
Prepare for health care costs and long-term care
Health costs can rise as your needs change. Medicare helps cover many services, yet premiums, copays, dental work, and extended support can add to your expenses. Include these costs in your retirement plan before you rely on savings or monthly income.
Budget for Medicare expenses and supplemental coverage
Medicare does not cover every expense. Review supplemental insurance and its limits. Fidelity estimates that a 65-year-old may need $185,500 in after-tax savings for health costs in 2026. A dedicated cushion can help protect your other assets.
- Estimate premiums, copays, dental costs, and supplemental coverage.
- Include long-term care in your retirement planning. Assisted living or nursing-home support may reduce savings.
- Compare long-term care insurance premiums, limits, and covered settings.
- Check how insurance could help protect your income and other assets.
- Review your costs as health and care needs change.
Long-term care policies can help pay for support in an assisted-living facility or nursing home. Read each policy closely, since coverage varies. Early review gives you more time to weigh options.
Protect your assets with insurance and estate planning
Protection works best when your coverage and estate documents support the same goals. Review life policies, long-term-care coverage, and other safeguards together. This can help protect your assets and family if care costs rise or income changes.
Long-term care insurance is designed to help cover assisted-living or nursing-home costs. These bills may draw down retirement savings. Permanent policies, including whole life and universal life, may build cash value. A policy loan can give you access to money, but an unpaid balance may reduce its death benefit.
Your estate plan can state how property and savings pass to loved ones. Consider possible tax effects, beneficiary designations, and whether documents still reflect your goals. Review these choices as your retirement needs change.
- Compare life, long-term-care, and other coverage with your assets, income, and expected expenses.
- An estate-planning professional can review wills, trusts, beneficiaries, and protection strategies. Ask how each choice supports your current retirement goals and estate priorities.
Keep your documents and coverage aligned as your needs evolve.
Review your retirement plan and get professional guidance
Your needs can shift over time, so review your retirement plan at least once a year. Check it again after a major life change, such as a move, job change, or health issue. Update your retirement goals, expenses, and withdrawals as needed.
Make each yearly review count
Check whether income sources, account balances, and investments still support your spending. Track progress toward retirement savings needs, then adjust your strategy if the numbers change.
- Revisit tax assumptions, Social Security timing, and required distributions.
- Set clear next steps, such as rebalancing a portfolio or changing contributions.
- Review how withdrawals affect your goals and available money.
A qualified advisor can help you assess complex choices. SmartAsset’s free matching tool connects you with up to three local fiduciary advisors. Review advisor profiles, then arrange an introductory call or meeting before you choose an advisor.
Use each review to keep your retirement plans aligned with your life. A steady routine can help you track changes and make informed decisions about your assets, accounts, and income.
Conclusion
A confident next chapter starts with clear priorities, a workable budget, and a sound view of what your savings can support. Your retirement plan should connect your resources to the life you want, not a fixed target.
Blend Social Security, pensions, and investment withdrawals to cover core costs while leaving room to adjust. Include taxes, health care, long-term care, and inflation when you test whether your retirement income can last. Small changes today can protect choices later.
Review your approach each year, and seek professional advice when goals, income, or circumstances change. Steady retirement planning can help you make choices that reflect your priorities. Keep retirement planning flexible as your needs evolve.

