
How an advisor gets paid can shape the guidance you receive. Fee-only financial advisors earn compensation directly from you, not commissions on financial products. NAPFA describes three broad models: commission-based, commission-and-fee, and fee-only. Knowing the difference can help you ask better questions as you compare advisors.
Fee arrangements can vary, too. You may pay by the hour, use a retainer, pay a flat fee, or choose a one-time planning engagement. Some planners charge a percentage of assets they manage. These options give you a starting point for comparing fees and services.
Good financial planning can reach beyond investment choices. Retirement, taxes, insurance, and estate decisions often connect, so your plan should reflect your goals. Fee structure matters, but so do fiduciary responsibility and how compensation may affect recommendations. This guide will help you weigh services, costs, and fit before you choose a planner.
Key Takeaways
- Fee-only advisors receive payment directly from clients.
- NAPFA identifies three broad compensation models.
- Payment options include hourly, retainer, flat, and asset-based fees.
- Some planners offer one-time planning engagements.
- Planning may include retirement, tax, insurance, and estate needs.
- Review services, fiduciary duty, and compensation before you decide.
What Fee-only financial advisors Do
A fee-only financial advisor can help you turn goals into clear steps. NAPFA members accept no commissions for their work. They receive direct client payments for advice, plan implementation, and ongoing asset management. This differs from compensation tied to product sales.
Service options vary by firm. Financial planning may cover retirement, investments, insurance and risk, taxes, estate coordination, business needs, and cash flow. Some planners also provide portfolio management or ongoing advisory support. Ask which services fit your needs.
Planning and Investment Management Services
A broader plan can connect wealth management choices with your daily cash needs. For example, an insurance review may help you assess risk, while tax-aware strategies can guide investment decisions. A certified financial planner or another professional may deliver these services, so confirm credentials and who will work with you.
How Fiduciary Guidance Supports Your Interests
NAPFA describes fiduciaries as putting clients’ best interests first, rather than relying only on a suitability standard. This duty can help you understand why a recommendation fits your goals. Still, confirm the scope of the relationship and how the planner supports your financial plan.
| Planning area | Possible service | What to confirm |
|---|---|---|
| Retirement and cash flow | Income and distribution planning | Whether support is ongoing |
| Investments and taxes | Portfolio and tax-aware strategies | Who manages the assets |
| Insurance and estate | Risk review and estate coordination | Which specialists are involved |
How Fee-Only Compensation Works
Your quote may reflect the work you need and how long you need support. NAPFA says a fee-only financial planner may charge directly for advice, plan implementation, or ongoing management of assets. Ask what each charge covers before you compare firms.
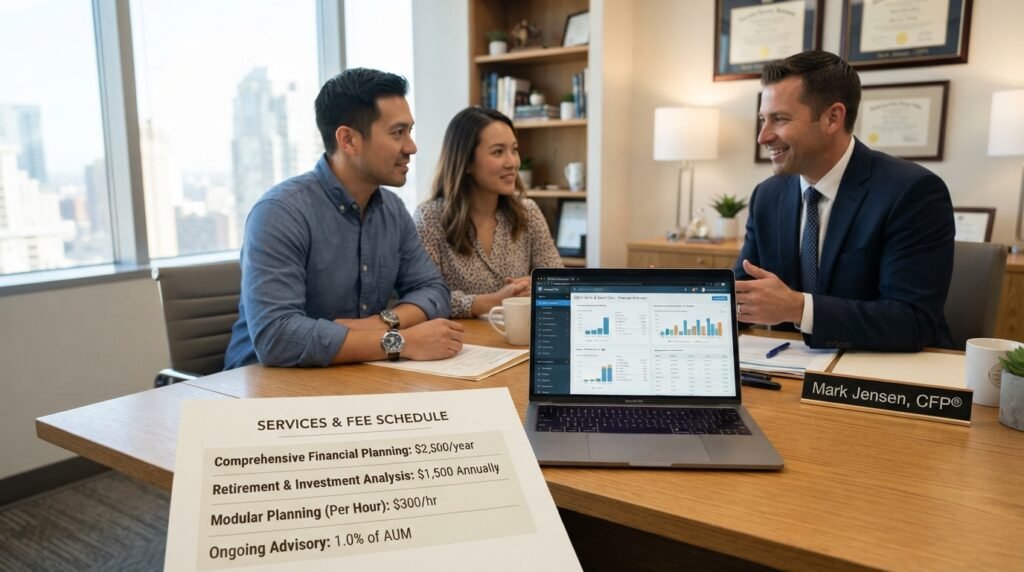
Assets Under Management, Flat, Hourly, and Retainer Fees
With assets under management, the advisor charges a percentage of the assets managed. Ask how the firm sets that percentage and whether it changes at different asset levels. This structure often creates recurring advisory fees tied to account value.
A flat fee covers a defined service or project. Hourly fees reflect time spent, while a retainer may cover ongoing access or planning. A one-time planning engagement is another option. These formats can help you understand compensation without relying on commissions from products.
Before you agree, ask whether fees cover investment management, financial planning, or both. Also ask if any recommended products involve commissions. Clear answers help you compare strategies and see how your client relationship may change over time.
| Fee format | How charges work | What to ask |
|---|---|---|
| Assets under management | Percentage of managed assets | How is the percentage calculated? |
| Flat or one-time | Set charge for defined planning work | Which services are included? |
| Hourly or retainer | Time-based or recurring payment | What support does the fee cover? |
Fee-Only vs. Fee-Based Financial Advisors
A firm’s payment label can show who pays it, but not the full scope of its work. NAPFA identifies three broad models: commission-based, commission-and-fee, and fee-only. Under the fee-only structure, clients pay directly, and the advisor does not earn commissions from products.
Fee-based financial firms may charge service fees and receive commissions tied to products or strategies. Insurance is one example: a recommendation may involve a policy that pays a commission. Ask when commissions apply and how the firm manages any conflict with your best interests.
- Both models may include broad planning or investment-focused management.
- Services, fee structure, and ongoing support vary by firm.
- CPC Wealth Management describes its work as fee-based wealth management and planning.
That example shows why labels alone do not tell you how compensation works. Before you hire an advisor, ask which products may generate commissions, who receives them, and whether fees cover planning, asset management, or both. Clear answers help you compare firms and understand what you will pay.
How to Evaluate an Advisor and Find the Right Fit
Choosing a planner takes more than checking a title. Use clear questions to see whether the person’s approach, costs, and support match your needs.
Questions to Ask About Fees, Services, and Conflicts
Ask how a fee-only financial advisor earns pay, when commissions apply, and whether they act as a fiduciary. Confirm which services the fee covers and how often the planner reviews your financial plan.
Ask who will support you over time. A useful planning process may link retirement, investment management, insurance, taxes, estate coordination, business needs, and cash flow.
Compare Planning Approach, Transparency, and Ongoing Support
Directories can help you find names, but review their disclosures. Advisorology, LLC says it may receive marketing fees from listed advisors and has a related material conflict of interest.
“Informational and educational, not as a source of investment or legal advice.”
Use directory details as a starting point. Compare the fee structure, services, and communication plan before you choose.
| What to compare | Question to ask | Why it matters |
|---|---|---|
| Compensation | When do commissions apply? | Reveals possible conflicts |
| Planning | Which needs does the plan cover? | Shows how well services fit your goals |
| Ongoing support | Who reviews your plan and when? | Sets expectations for future contact |
Conclusion
Your best choice comes from how well the working relationship supports your priorities. Fee-only advisors receive direct payment from clients and do not earn product commissions; fee-based arrangements may include them. NAPFA lists hourly, retainer, percentage-of-assets, and flat-fee options. Yet payment structure alone cannot show the full scope of financial planning or wealth management, since services differ by firm.
Before you hire a financial advisor, confirm fiduciary status. Ask which services the fee covers, whether commissions apply, how often the planner reviews your plan, and what long-term support you can expect. Compare transparency, planning scope, fees, and investment management to find a fit for your goals. The right client relationship should match your needs, not just a label.

