
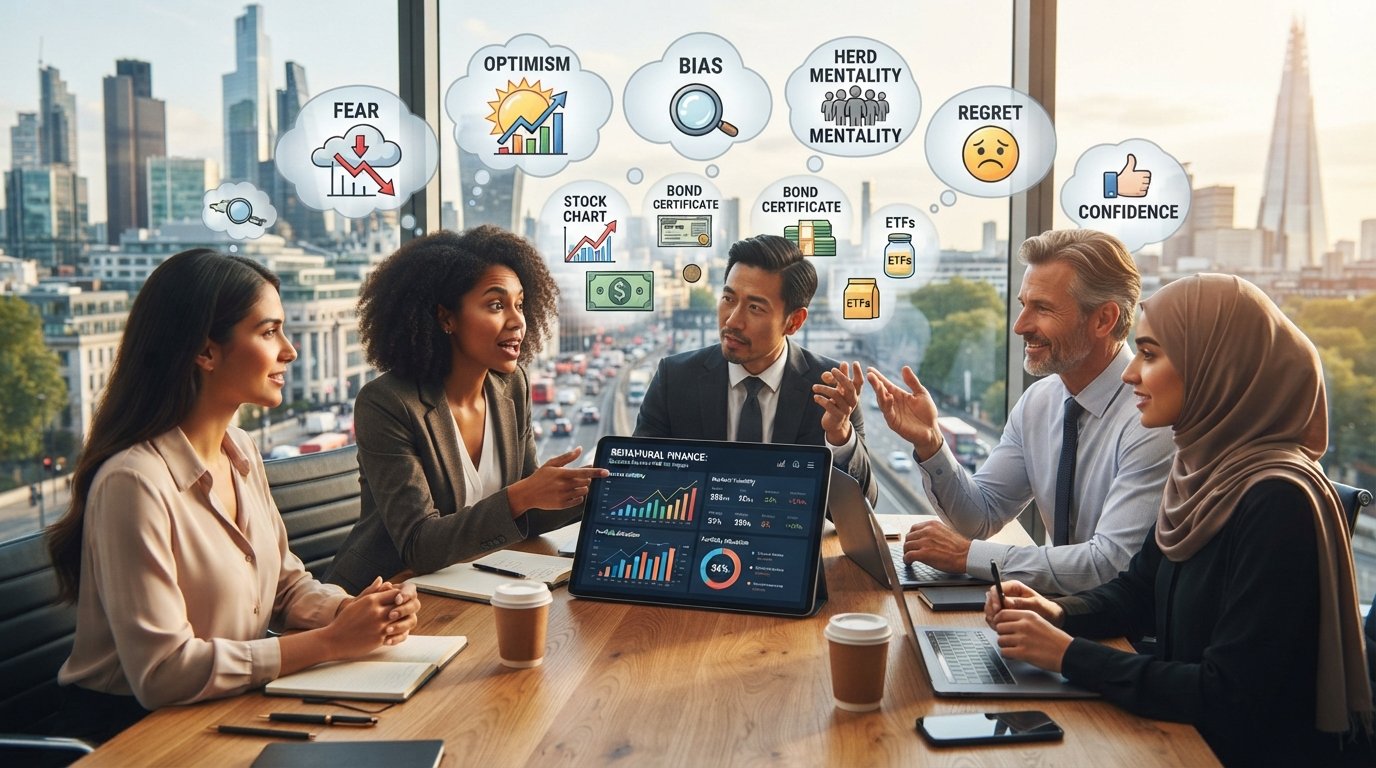
Money choices may seem like math, but people do not always follow a model or the latest data. Your goals, mood, and past experiences can shape how you respond to risk. Understanding those forces can help you make more thoughtful financial decisions.
Behavioral finance studies how psychology and emotions affect money choices. The field emerged in the 1980s, challenging the idea that people always act in fully rational ways. It also offers a useful lens for spotting biases that may shape your behavior.
Market uncertainty can make this topic feel especially relevant. News and sudden changes may prompt you to react before you weigh your options. By learning core concepts, you can pause, assess the facts, and choose a response that fits your needs.
This article moves from key ideas to practical strategies, including approaches used by financial advisors such as Kate Freeman, CFA, at UBS. You’ll find ways to reflect on your choices and use evidence with greater care.
Key Takeaways
- Psychology and emotions can shape money choices.
- The field took shape in the 1980s.
- People may not act as models predict.
- Recognizing biases can help you review choices.
- Market events can affect how you respond.
- Practical strategies can help you make more considered choices.
What Behavioral Finance Insights Reveal About Your Financial Decisions
In the early 1960s, many economists assumed people weighed options logically and aimed to gain the most value. Behavioral finance challenges that tidy model: real choices can reflect limits, feelings, and context.
How Psychology and Economics Explain Financial Behavior
The field brings economics together with biology and psychology to study how people respond to risk, rewards, and uncertainty. This mix helps research identify patterns in investor behavior and the way investors assess options.
These insights help you see why a choice may differ from a purely logical model. They also show how individual needs and past experience can shape decisions.
Why Emotions and Biases Can Override Data
Even when market data and useful information are available, cognitive biases can shape what an investor notices, trusts, or ignores. Fear or confidence may outweigh evidence.
Behavioral finance research offers a way to examine these reactions. Seeing how psychology affects your choices gives context for specific biases documented by researchers, which the next section explores.
Common Biases That Shape How Investors Make Decisions
Several patterns can affect the way you judge risk and value. Behavioral finance research helps explain these habits, but spotting them in your own choices takes attention. Noticing a bias gives you a chance to pause before acting.
Loss Aversion and the Fear of Investment Losses
Loss aversion means a loss can feel more painful than an equal gain feels pleasing. That discomfort may lead you to avoid reasonable risks or hold an investment too long. Investors may buy after a long rally, then sell after a sharp decline, turning emotions into costly outcomes.
Herd Behavior and Following the Market Crowd
Herd behavior is the tendency to follow others into the same sectors or markets. When many people rush toward one investment, you may feel pressure to join them without weighing your own goals.
Anchoring, Recency Bias, and Overconfidence
Anchoring keeps you tied to a perceived value, even when new information suggests conditions have changed. Recency bias can make recent market moves seem likely to continue. Overconfidence may lead you to trust your judgment more than the evidence supports. Together, these biases can shape decisions and affect investing outcomes. Review the facts, not just the latest price or what others expect.
How Emotions Influence Investment Choices During Market Volatility
Geopolitical events, recession fears, and market volatility can unsettle investors. When headlines feel urgent, fear or excitement may push you to act before you review the available information and data. Behavioral finance helps explain why emotions can shape decisions, even when you aim to follow a plan.
Why Fear and Excitement Can Trigger Hasty Decisions
Loss aversion makes losses feel more painful than equal gains feel good. During volatile markets, that reaction can affect how you judge risk. For example, investors may buy after a long rally, then sell after a sharp decline. This behavior can turn short-term market moves into costly choices.
“A market move is a reason to review your plan, not an order to act.”
Pause before changing course. Give yourself time to assess conditions over time, not just the latest price. This simple step can help investors make calmer decisions and support steadier investing outcomes.
| Market signal | Possible reaction | Useful pause |
|---|---|---|
| Long rally | Excitement may prompt a rushed purchase | Check your goals and risk level |
| Sharp decline | Fear may prompt a rushed sale | Review your plan and current facts |
Strategies to Make More Rational Financial Decisions
A clear routine can help you respond with care instead of reacting to a headline. These strategies turn behavioral finance insights into practical steps you can use when choices feel urgent.
Pause, Review Information, and Follow a Coherent Plan
Before you change an investment, pause and review the facts. Check whether the information is current, then compare the choice with your plan. A written plan can keep investors focused on their goals, time frame, and risk level.
“Pause, check the facts, and let your plan guide the next step.”
This approach will not prevent every mistake. Still, it can limit emotional behavior and help you make rational choices based on your priorities.
Use an Advisor to Challenge Emotional Choices
An advisor can help sort useful signals from short-term noise and flag decisions that seem out of step with your goals. Kate Freeman, CFA, a Financial Advisor at UBS, stresses the value of spotting a client’s biases and building trust so they can discuss them openly.
Good advice supports your judgment; it does not replace it. Investors and finance professionals can use these strategies as tools for calmer decision-making, not as a promise of a certain outcome. Treat awareness as part of sound investment management, and revisit your plan as your needs change.
Applying Behavioral Finance Insights to Your Goals and Risk Management
Your investment plan should reflect both your financial priorities and the way you respond to uncertainty. Behavioral finance helps you connect personal goals with a risk management approach that accounts for emotional tendencies. That link can matter during market volatility, when fear of loss or overconfidence may sway even experienced investors.
- Set clear goals and review them as your needs change.
- Check for biases before changing investments or reacting to others.
- Use research and a steady process to support rational decisions.
Sreeni Meka, CFA, a Financial Advisor at Lakeland Wealth Management, emphasizes understanding client psychology when making investment choices. Luis Gonzali, CFA, Vice President and Co-Chief of Investments at Franklin Templeton, Mexico, describes behavioral finance as enlightening and useful in his daily work. Their views show how these strategies can inform the choices of investors and professionals.
“A plan works best when it reflects your goals, your needs, and your response to risk.”
An ongoing advisor relationship can help you get clear advice and personal support over time. Clients may value that connection more than cost or past performance. Keep your goals central as markets shift, and revisit your investment management plan when your circumstances change.
Conclusion
Recognizing how behavioral finance shapes your decisions gives you a reason to pause and test your assumptions. That pause can help you choose with care instead of reacting to a sudden market move.
When you notice bias and emotion, you can avoid choices that work against your plan. Investors at every experience level, including those with deep market knowledge, can feel pressure during uncertain periods. Reviewing reliable information and following a clear process can keep risk and goals in view, supporting steadier outcomes over time.
Use these strategies consistently. Let research inform your next step, and seek an advisor who understands your needs when extra perspective would help. The insights you gain can support thoughtful choices through changing markets. Awareness is a practice, not a one-time task.

